At a glance
The Labuan Financial Services Authority placed Asia Pacific Investment Bank Ltd under a business restriction on September 7, 2026, citing minimum capital and/or other regulatory non-compliance, before revoking its investment-banking licence on September 29. The article explains that the published notices establish the regulatory chronology but do not disclose APIB-specific findings, post-revocation arrangements or a causal connection to a separate US$16 million SBLC criminal case.
The revocation of Asia Pacific Investment Bank Ltd’s (APIB) investment-banking licence is a confirmed regulatory event. The position of the US$16 million standby letter of credit associated with the bank is a separate question that cannot be answered from the revocation notice alone. Labuan FSA’s enforcement register records that APIB’s licence was revoked on September 29, 2026. The notice does not set out the terms of the SBLC, identify its beneficiary, describe any demand for payment or determine the status of any obligation under the instrument.
The criminal proceedings provide a limited but important part of the public record. On September 30, two former APIB employees pleaded not guilty to charges arising from allegations that they deceived the bank about approval for the SBLC and processed it through their respective maker and checker roles in the SWIFT system. The alleged offence dates to November 9, 2023. Those allegations remain for the court to determine. They do not establish whether a beneficiary made a demand under the instrument, whether the demand complied with its terms, or what legal consequences followed from the document’s issuance.
A standby letter of credit is governed by its wording and the applicable legal framework. The International Chamber of Commerce’s UCP 600 rules apply to a documentary credit, including a standby to the extent applicable, when the instrument expressly incorporates them. Article 7 addresses the issuing bank’s undertaking to honour a complying presentation. Other rule sets, including ISP98, may be relevant where expressly incorporated. The governing framework and the precise text of the APIB instrument have not been established by the sources cited in this series, so no conclusion can be reached here about which rules govern this particular SBLC or whether a particular demand would meet its conditions.
The decisive documents would include the complete instrument and amendments, its stated expiry date, presentation conditions, governing-law clause and any incorporated rules. The applicant’s agreement with the issuer, relevant bank-to-bank communications, any demand and the response to it would also matter. Those records could establish whether a demand was made, whether the instrument had expired, whether a presentation was compliant and what position the issuer or other parties took. In their absence, it would be inaccurate to claim that the US$16 million is currently payable, that payment has been refused, or that a loss has crystallised.
Revocation also needs to be distinguished from the termination of a contractual obligation. The published notice confirms the loss of APIB’s licence; it does not say that all existing contracts were extinguished or that the bank’s obligations under a previously issued instrument automatically disappeared. The consequences of revocation for any particular obligation depend on the instrument, applicable law and any relevant regulatory or court directions. The same applies to any question about how outstanding business is administered after the licence is revoked.
Nor does the fact that Asia Digital Bank Ltd (ADB) was publicly described in 2021 as APIB’s wholly owned subsidiary establish that ADB is responsible for the SBLC. ADB has its own corporate identity and its own Labuan investment-banking licence identified on its website. The public records reviewed do not establish that ADB issued, guaranteed or assumed the obligations of the instrument. Any assertion that ADB must pay, or that its assets are available to satisfy an APIB obligation, would require evidence of an applicable guarantee, contractual assumption, transfer or other legal basis.
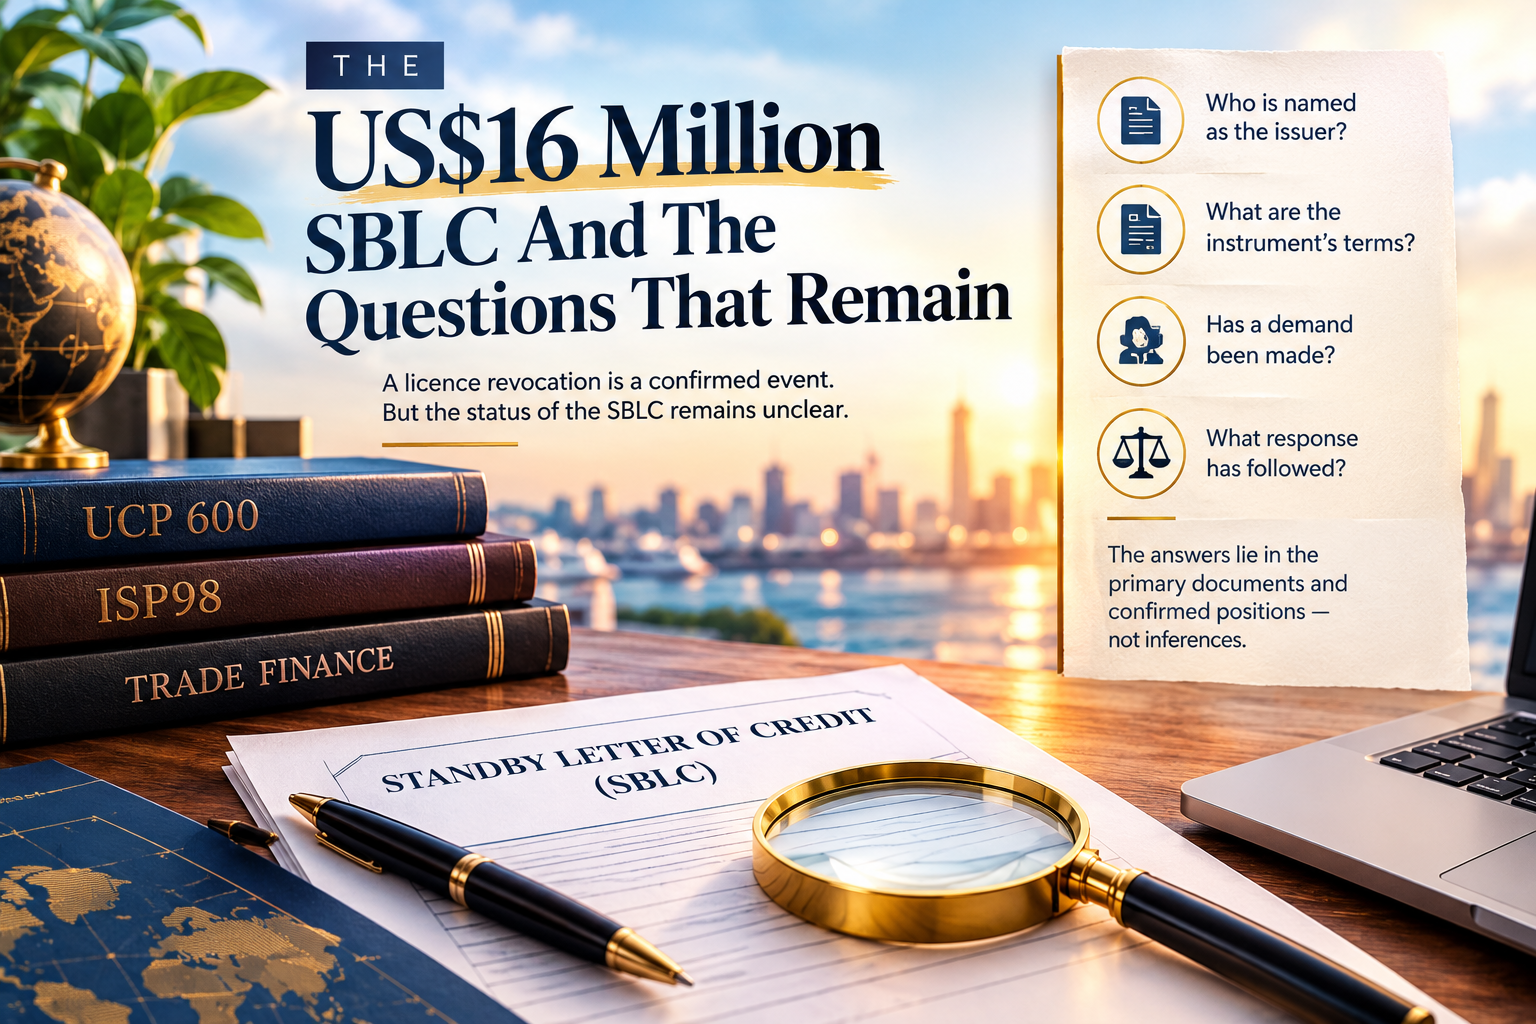
The public record therefore leaves the central financial question open. Who is named as issuer in the instrument, what are the instrument’s terms, has a demand been made, and what response has followed? Those questions should be answered from the primary documents and the parties’ confirmed positions, not inferred from the criminal charge or the regulatory action.
A licence revocation establishes a change in regulatory status. It does not, by itself, establish the fate of a particular standby letter of credit. The status of the US$16 million instrument can only be reported responsibly once the instrument, its governing terms and the relevant correspondence have been verified.