At a glance
Asia Pacific Investment Bank Ltd had its investment-banking licence revoked by the Labuan Financial Services Authority on September 29, 2026. The article examines why public regulatory notices alone cannot establish the location of APIB’s assets, liabilities, contractual obligations or any transfers involving associated entities. It stresses that audited accounts, corporate filings, contracts and transaction records must be examined before drawing conclusions about creditor impact or liability shifting.
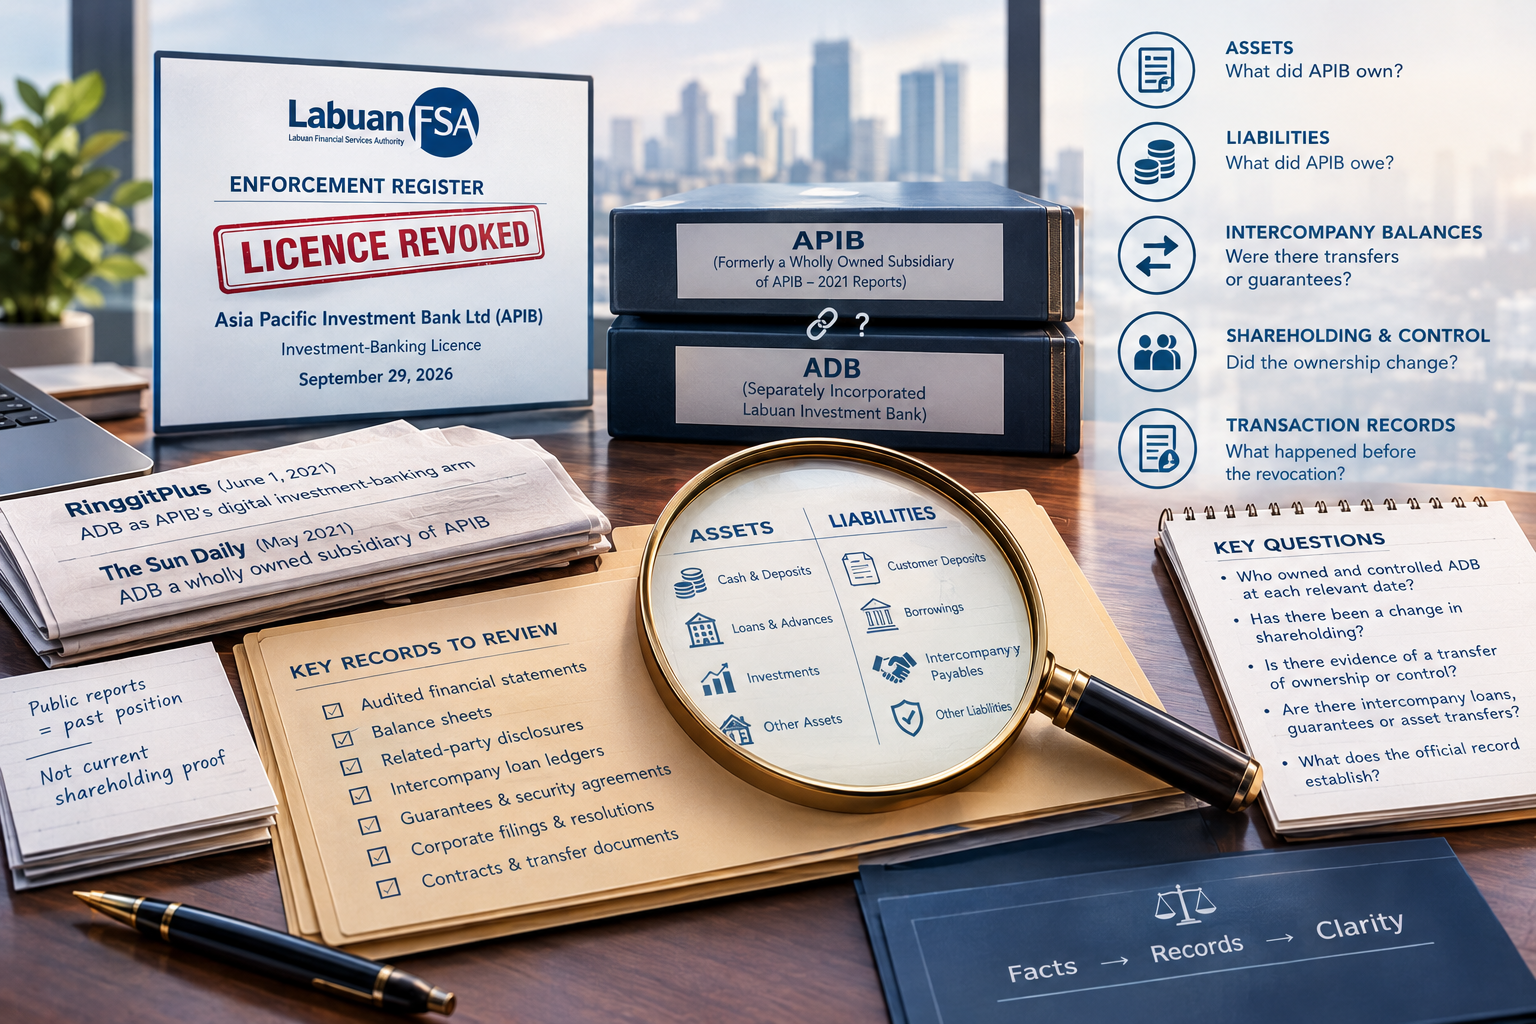
When a financial institution loses its licence, the regulatory event is clear. The position of its assets, contractual obligations, intercompany balances and creditors may be considerably less clear from a public notice alone. In the case of Asia Pacific Investment Bank Ltd (APIB), the Labuan Financial Services Authority’s enforcement register records the revocation of investment-banking licence on September 29, 2026. The register confirms the regulatory outcome, but it does not provide a public accounting of APIB’s assets, liabilities or the disposition of any business interests associated with the bank.
That gap should not be filled with assumptions. The available public record does not establish that APIB transferred assets to Asia Digital Bank Ltd (ADB) or another entity before the revocation. Nor does it establish that creditors were disadvantaged by a restructuring. Those are questions for records-based investigation, not conclusions that can be drawn merely because two institutions have been publicly associated with one another.
The corporate relationship between APIB and ADB nevertheless makes the underlying records relevant. In 2021, contemporary reports described ADB as a wholly owned subsidiary of APIB. ADB now identifies itself as a separately incorporated Labuan investment bank, while the Labuan FSA directory updated in July 2026 listed both institutions. The available material does not establish whether the reported shareholding subsequently changed. Establishing that history is a necessary first step before any assessment can be made of possible transfers, common control or intercompany exposure.
The relevant financial records would include audited accounts, balance sheets, related-party disclosures, intercompany loan ledgers, guarantees, security agreements and records of transfers involving material assets. Corporate filings could establish changes in share ownership or control. Contracts could identify whether another entity assumed a liability, guaranteed an obligation or acquired a particular asset. Any such transaction would then need to be examined in its own legal and commercial context, including its date, consideration, approvals and effect on existing contractual rights.
The US$16 million standby letter of credit involving APIB provides a specific reason to identify the bank’s relevant contractual exposure. Two former employees pleaded not guilty on September 30, 2026, to charges relating to alleged deception over the instrument. The prosecution’s allegations concern the circumstances in which the instrument was processed; they do not establish that assets were moved, that another entity assumed the obligation, or that the bank’s financial position was altered to frustrate a beneficiary. Those matters require separate evidence.
A further distinction is essential. Corporate affiliation does not automatically make one company liable for another company’s debts. Whether a parent, subsidiary, guarantor or transferee has obligations depends on the applicable contracts, corporate arrangements and legal principles. Any attempt to trace liability must begin with the instrument, the identity of its issuer, the relevant agreements and the actual corporate records.
The investigation should therefore establish what APIB owned, what it owed, what transactions it entered into before the revocation, and whether any documented transfer affected a particular creditor or contractual counterparty. If the records show no relevant transfer, that finding should be reported. If they disclose a transaction, its terms and legal effect should be assessed before any inference of impropriety is drawn.
The central issue is not whether assets must have moved. It is whether the available records permit a reliable account of where the assets and liabilities stood when APIB’s licence was revoked. Until the financial statements, transaction records and relevant corporate filings are examined, any claim that liabilities were shifted or creditors left behind would be premature.